Thursday, 2 November 2023

Moving on, part 2

  I'm so glad you came by. But I have moved to two new sites.

My main blog can now be found at ralphturnerwriter.com

And anything to do with the revival in Leicester can be found at revivalinleicester.com

I do hope you will join me on our continuing journey together.

Monday, 27 May 2019

YOU CAN STILL FIND ME.....

I've retired from the pensions industry now (though if you have the odd trustee position, do shout!) So that means this blog is closed.

There's lots here though, especially to do with pensions communications, so do take a look through. And we're still not communicating well to members!

And finally, if you want to say 'hi', you can reach me at ralphturnerwriter@gmail.com. And my general blog is still operating: Mountain Climbing for Beginners. I hope to see you there.

"Never measure the height of a mountain until you have reached the top. Then you will see how low it was."
Dag Hammarskjold 

Wednesday, 20 June 2018

Brexit Mania Hits Pensions


The future of the well supported Pensions Dashboard is in doubt. And Brexit is the reason. The Government seem unable to consider anything other than Europe and our relationship within (or without) it. It means good local policy is being side-lined.

There’s a consensus that legislation is needed to introduce a compulsory Dashboard- a go-to place for all our pensions, held in one place and with all providers required to work with it . Everything in one place and set out in a standard way: What’s not to like?

Limited availability in the parliamentary calendar means the compulsion may not happen- or not any time soon.

With the legislation beginning to slip into the long grass, the Department for Work and Pensions (DWP) feasibility report including the broad proposals, has also been delayed. Due in March, then ‘late spring’, it’s still not here. The DWP are now saying it will appear 'in due course.' Yea, right. And of course, the DWP have no real incentive without a Government willingness to push forward.

One of the best and most far reaching ideas in terms of clear pension’s communication is in danger of not happening, only partially happening, or completely happening but at a date so far in the future we may as well go argue about Brexit.

Monday, 29 January 2018

..And We Wonder Why We Have A Pensions Problem....

Number of Prime Ministers in last 20 years:  4

Number of Pension Ministers in last 20 years:  15

Average tenure of Prime Minister:  5 years

Average tenure of Pension Minister: 1 year, 4 months*


*This includes the impressive 5 year stint from Steve Webb.

Thursday, 26 October 2017

It’s Not Just About Costs

The announcement today from the Government with regard to cost transparency is welcome. It should not be hard for members to understand what they are paying – and what costs are being charged for both administration and investments.

There is one concern though- a rush to the lowest charges may not mean the best deal. There needs to be care involved in explaining costs. A higher administration charge in some cases may mean a local company DC plan can continue, rather than being swallowed up by one of the big providers, or by a master trust. And there’s a good reason for that additional cost if the result is a plan that is better suited to that company’s workforce, as well as it being better presented and explained.

As to investment costs being more transparent- about time too! But again, take care in explaining that lowest charges don’t always equate with best returns.

As employers and providers, we can’t just rely on costs being understood. Members need to understand the value of their pension plan, the fact that it’s tax efficient and that employer money is being paid in as well. These are basic things, but so often still misunderstood by a workforce that is apathetic to pensions. The employer and provider can’t afford the same apathy.

As always, pensions will remain complicated. And it's not just about costs. Good communication is key. Enthusiasm from the provider and employer sponsor is key too.

Monday, 11 September 2017

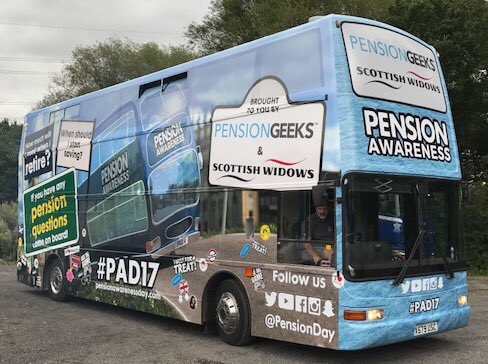
Pensions Awareness Day - On The Road


It’s year four. And it’s been quite a journey. From originally registering Pensions Awareness Day, to seeking support from the pensions industry (thank you!) to painting up a bus and taking it around the country…. It’s got bigger and better each year.

This year starts in Edinburgh, and the bus then moves on to Leeds, Birmingham, Cardiff and London. Over the week, we are expecting hundreds of people to come onto the bus, asking their questions about pensions. We will be giving away plenty of ‘freebies’ and with help from Pensions Wise, handing out loads of advice.

If you’re in the area, why not come over? This is the website with dates and times in each city:

PENSIONS AWARENESS DAY

As an industry, we’ve a long way to go before people are saving anywhere near enough for retirement. But we’re off and running. Join us!

Wednesday, 16 August 2017

Deferreds - The Poor Relations

I’m of that age. Time to start looking at what pensions I’ve got and to consider when to take them. It’s a bit of a shock to have reached such an age, I have to say! I’ve spent most of my career planning other people’s retirement and never really thought about planning my own. But there you go – time waits for no man and all that.

My first foray into my very own pension-land wasn’t such a success though. I approached a life and investment company that had taken over the liabilities of a plan I had been part of a long time back. And was rather surprised to be told I had no pension with them! I was able to produce a deferred pension statement, and all was sorted. But it does beg the question as to what would happen if I were less prepared. How many others fail to sort out deferred pensions due to poor record keeping? Or, more likely, having gone away and failed to notify the provider of the new address.

The usual tracing processes mean that eventually, the deferred member will (hopefully) be found and the benefits sorted out. But there’s no doubt that deferreds – especially in closed DB schemes – are the poor relations in terms of communication.

I hope that the new plans for a pensions dashboard will help rectify this. And there’s legislation on the way requiring an annual statement for deferreds as well. The more frequent use of emails in record keeping is helpful too, as many people may move house but not change their email address.

Nevertheless, as I found out personally, deferreds need a bit more attention.

As to the amount I’ll be getting, well let's say I won’t be fully retiring just yet!


Tuesday, 20 June 2017

Regulator in Danger of Decreasing Pension Membership

At an SPS conference last week, the Regulator's spokesperson talked of the need to encourage consolidation of pension schemes and how to remove the barriers to consolidation.

At the end of her talk, I challenged her. Is she saying 'big is good'?

She assured me she wasn't saying 'big is good' but then went on to repeat what she had said in the talk- the need for lower fees and economies of scale.

There's a problem with this for the small and medium sized employers that value the pension plans they have. They have put the plans in place for a reason, they value them and they promote them to their staff, with a high take-up. they own the plan- it bears their name. It was designed by them.

The moment they are forced to consolidate into something bigger, they lose the 'family touch'. They lose the ownership.

We have seen over the years what happens when the MD or FD is excluded from the scheme they own as a company. Almost inevitably, they start to devalue the scheme and lose ownership of it.

The same will happen with the Regulator's plan for consolidation. Quality plans will be closed - squandered at the altar of spurious reductions in admin and investment fees.

Ownership is lost. Membership decreases.

An own goal for the Regulator.

Wednesday, 17 May 2017

Dear Next Government.....

I’m not sure that pensions will be one of the major battle grounds in this election, and if it is, it may tend to be around the ‘triple lock’ headlines.

That would be missing the point. We need clarity form the next government in terms of the communication of pension plans. I appreciate the initiatives towards one design for future benefit statements, but the sooner the better.

Clarity on the future management and promotion of auto-enrolment is key. As is confirmation of state pension benefits and ages.

All this should lead to a harmonised approach to communicating pension benefits. Too many benefit statements have reams of small print. Most of it is legislative. Some of it is pension lawyers having too strong a say in the look and feel of communications.

It doesn’t help that we have the dreaded statutory money purchase illustrations. Loads of caveats. Tons of small print. So unhelpful.

Dear next government…. Please simplify communications. Cut the small print. Clarify the main figures. Help people understand.

Wednesday, 29 March 2017

With apologies....

With apologies to my actuarial and marketing friends......

Two people are flying in a hot air balloon and realise they are lost. They see a man on the ground, so they navigate the balloon to where they can speak to him. They yell to him, "Can you help us – we’re lost."

The man on the ground replies, "You’re in a hot air balloon, about two hundred feet off the ground." One of the people in the balloon replies to the man on the ground, "You must be an actuary. You gave us information that is accurate, but completely useless."

The actuary on the ground yells to the people in the balloon, "you must be in marketing."

They yell back, "yes, how did you know?"

The actuary says, "well, you’re in the same situation you were in before you talked to me, but now it’s my fault."

Tuesday, 7 March 2017

Mergers - Who Really Benefits?

One of the things that intrigued me about the 20 year anniversary edition of Professional Pensions was the article by JonathanStapleton looking back at the names of the companies that were advertising in that very first issue.

Names that have now disappeared: Hill Samuel. GAN. Dibb Lupton Alsop. Kaupthing Singer & Friedlander. Capel-Cure Myers. Gartmore. Abbey Life. Hogg Robinson. Morgan Grenfell. Hewitt. Norwich Union.

All gone- and mainly forgotten in a plethora of mergers and takeovers over the years.

And now another one. Aberdeen and Standard Life are to merge.

I suspect the name Standard Life will survive. But then I thought that of Norwich Union before it gave way to the clinically globalised name Aviva.

Pensions Age Magazine quotes the marketing gobbledygook: ‘[the] merger would harness Standard Life and Aberdeen’s complementary, market leading investment and savings capabilities which would deliver a compelling and comprehensive product offering for clients covering developed and emerging market equities and fixed income, multi-asset, real estate and alternatives.’

They mention synergies. And surely there will be. In the way of job losses for the back-room functions mainly. But what about the investment managers- the individuals tasked with making the strategic decisions? Changes are not always welcomed to the people that do the work. They are used to a system, used to a style. When that style changes, so might their appreciation of the job they do. This in turn can affect returns for clients.

Synergies? Cost savings more like. And cost savings don’t always mean benefits for clients.

Thursday, 9 February 2017

The Daily Mail Fabricates News - Not so new news

The news out today that the Daily Mail fabricates news is not such new news. Working in the pensions industry, their regular pension headlines have been the bane of many a pensions manager.

The Mail had the ability to pick up on a half-truth and fabricate a complete story out of it. The results were usually concerned members of pension schemes panicking that they have the right plans in place.

The negative Mail headlines for pensions caused unnecessary grief and may well have stopped employees from joining a pension plan they should have been part of.

The poor journalism on display at the Mail has found them out.

Monday, 9 January 2017

The Video Clip Every Boss Should Watch

This blog is mainly about pensions and communicating pensions. It's usually a short piece with a few links for the more interested. It's short because we don't have the patience to read or listen- especially if we are accessing this at work.

So this is different. It's a 15 minute video from Simon Sinek and it relates to  hiring 'Millennials' - ie those born in 1984 and later.

There is so much sense in what he says. If you're an employer, a department boss, you work in recruitment, or in HR, I recommend you take the time to view it. I appreciate it's longer than something you'd normally watch in work time, but you will be rewarded with some excellent insights. Enjoy.


Tuesday, 3 January 2017

New Year Wishes

There will be a lot in the pensions press over the next few weeks relating to the New Year. A New Year goes along with New Year resolutions and wishes.

In pension terms, wishes are likely to revolve around simplified administration, easier investment access to difficult products and a plea to the politicians to be left alone. Some wishes may get granted- the current initiatives relating to data management are both welcome and likely to succeed. Investment products will simplify. And possibly – possibly – the Chancellor has enough on his plate not to interfere further in pensions.

The missing wish, though, is always there. Every year. Better communications. Too many people don’t know enough about their pension. Too many people without a pension are not concerned enough to do something about it.  

About now, with New Year resolutions in mind, the pension manager is returning to work and budgeting to communicate more efficiently. Maybe some focus groups. Maybe a survey. Maybe different methods of communicating including print and electronic.

Somewhere around mid-February, reality and the new budget process sets in and the dreams are forgotten. Another year of ‘doing what we’ve always done’ at as low a cost as possible.

So here’s a New Year wish. Please keep communications in your new year budget. Budget to use some pension communication experts. And change next years’ wishes.

Tuesday, 1 November 2016

The Barrier of Words

As passionate pensions people we want to communicate well. We want people to understand their pension and appreciate its value. But we are often stopped from communicating well by our own blind spots. In fact our words can be a barrier to getting the message across.

The Technical Barrier

Too often we assume we are being clear with our pension communications when it is nothing but gobbledygook to the recipient. We are so wrapped up in the industry we work in, we are not aware of the pension jargon we are using. Glossaries help, but better to write plainly and assume the reader knows nothing about the subject. If you talk about ‘hedging’ your investments, people are likely to be thinking of a green bush in the garden. If you speak of commutation, people will think you are talking about travelling to work…. You get the picture!

The Cultural Barrier

This is a more subtle communication issue. Not all companies are the same. Many may be UK companies and have a certain style of communicating. Others may be US companies- generally the business language is sharper and more to the point.

I work part time for a community based charity. Here the language is very different to anything I have experienced in the commercial world. You can’t just dive in to the issue you want to email on, for example. There has to be a bit of a ‘how are you’ and a conversation would typically end with ‘blessings’ rather than ‘cheers’ or ‘yours sincerely.’

So when you’re speaking about pensions – typically a ‘foreign language’ to any organisation, it’s important to first asses the culture of the company you are working with.

The Functional Barrier

As an occasional consultant for Pension Geeks, it’s interesting pitching business. No matter what the potential client may say, you are being assessed against the incumbent communications company. And, sometimes without the client being aware of it, they are expecting you to be the same, and possibly to charge the same. (As we’re smaller with fewer overheads, the fees are usually a good conversation to have).

That same functional barrier can work in presenting pensions to a non-specialist audience. They have an expectation that they won’t understand it, sadly based on earlier pension events or (often inaccurate) articles they have read in the press.

Words can be a barrier. And there’s the challenge!

Thursday, 8 September 2016

Majoring on the Minors

My good friend Henry Tapper makes an interesting point in one of his recent blogs (where does he get the energy to write so much?!) He points out that we keep going on about investment freedom of choice when most people just need a good default choice.

That’s backed up by what we find on the Pensions Awareness Day bus. So many people come on board with pension questions. And so many more with a simple statement: ‘Tell me what to do.’

We are catering too often for the financial expert, and not enough for the man or woman on the street. It may feel uncomfortable to ‘tell’ people what to do but that’s what they want.

If we could just put as much energy into developing effective default options as we do into developing the next big investment idea that is only of interest to the minority, we really would be getting somewhere.

Monday, 18 July 2016

Good-bye Ros


I wasn’t a fan of the Ros Altmann appointment as Pension Minister and am not unhappy to see her go. She has been a good champion of pension’s miss-selling and other inadequacies in our present system, but she has also been a champion of her own profile. A bit of self-promotion is okay so long as you get the right things done. But in her time as Pension Minister, frankly, she didn’t.
She appeared to put on hold Steve Webb’s Defined Ambition agenda but didn’t push through anything else in its place. She was caught out, seemingly, by Treasury initiatives around lifetime ISAs, and her most publicised comments during her tenure were not on the subject of pensions but her critical observations relating to her then-boss Iain Duncan-Smith.
As she continues to speak for pensions from her seat in the House of Lords, it is likely to be as a populist voice for change, but without the detailed knowledge of how to do it- something else that exposed her during her time as minister.
And I expect we will see a return to the OTT headlines in the Daily Express with Ros Altmann quoted as the expert. I suspect that many of these headlines in the past were her own creations and necessarily lessened whilst she was Pension Minister.
The more junior appointments that follow her tenure suggest a greater hold of pension policy at the Treasury as well as reflecting a perceived government view that pensions doesn’t need high profile ministers.

Thursday, 2 June 2016

Benefits that Drive Value

I met a Finance Director of a medium sized business recently. In our brief conversation, he made it clear he did not value the benefits his company provided to staff and saw them simply as an additional overhead.

If I’d had longer to talk, I’d have said more than I did. This is my follow up letter. (Not actually sent as I didn’t get his details!)


Dear Finance Director

It was good to meet you the other day.

I appreciate our conversation was a brief one, but if I’d had longer to chat, this is what I would have said….

I understand business is tough and from your point of view, additional benefits on top of salary are just overheads to be dealt with. But have you considered what you could do with those benefits at little extra cost to you?

Most employees don’t value their benefits either- mostly because employers don’t communicate them too well. I’m guessing that would include you- why communicate what you don’t value as a business manager? But the benefits all have value. The pension has matching employer contributions. That’s like free pay to your staff. Even the flexible holidays have a value, and the discounted affinity benefits have little cost to you but significant value to those who use them.

I guess I’m asking you to have another look at what you offer.  With the right communication, you can turn benefits from perceived business costs to providing a competitive edge for your company. Good benefits properly explained promote your business above and beyond your competitor who does not have those benefits- or does not bother communicating them. Small communication costs can provide a significant competitive edge, driven from staff wellbeing and a value well beyond the benefits themselves.

Benefits don’t have to be overheads. They can be your business case for future profitability.

Yours sincerely

Friday, 29 April 2016

The Reason for Wrong Decisions

Well done to Darren Philp of People's Pension for the excellent presentation at this week's Pension Age Conference. He spoke on reasons people make the wrong decisions. So with some commentary of my own,  here's hoping I was listening properly:

1. Present Bias
This is simply the feeling that I can have the money now, take it out, use it, not save it.

2. Ostrich Effect
Head in the sand and the pension decisions may go away.

3. Optimism Bias
I really won't need to save that much as what I have will bring in loads of interest. Alternatively... I really won't need much in retirement...

4. Complexity Aversion Bias
Too much choice! What to do? Nothing.

5. Bandwagon Effect
What's everyone else doing? That must be right....

6. Confirmation Effect
Can someone please confirm what's best for me? Just tell me what to do!

The solution to these issues lies in clear communication at a simple level, good 'defaults' and a good deal of persistence from the employer/provider!

Tuesday, 26 April 2016

Belonging

There's some good thinking from LCP on the Brexit issue this week. In the end it may not be to do with economics, but more to do with 'belonging'.

Do we want to be part of Europe or not? To be on the outside may not be the best place for us in the long term, even if in the short term, the financials are not so bad as they are sometimes portrayed.

I prefer belonging to pulling up metaphorical drawbridges, but as the LCP article suggests, there's a lot of emotion and hot air in this debate. The Churchill quote is apposite:  “A fanatic is one who can’t change his mind and won’t change the subject”.