Showing posts with label retirement income. Show all posts

Monday, 11 September 2017

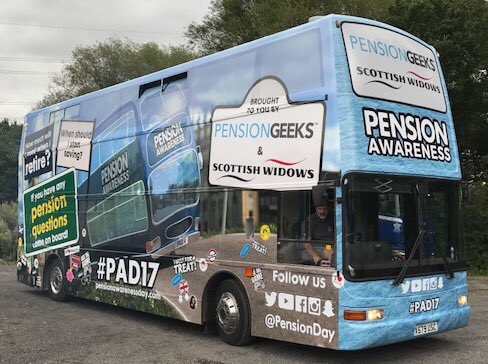
Pensions Awareness Day - On The Road


It’s year four. And it’s been quite a journey. From originally registering Pensions Awareness Day, to seeking support from the pensions industry (thank you!) to painting up a bus and taking it around the country…. It’s got bigger and better each year.

This year starts in Edinburgh, and the bus then moves on to Leeds, Birmingham, Cardiff and London. Over the week, we are expecting hundreds of people to come onto the bus, asking their questions about pensions. We will be giving away plenty of ‘freebies’ and with help from Pensions Wise, handing out loads of advice.

If you’re in the area, why not come over? This is the website with dates and times in each city:

PENSIONS AWARENESS DAY

As an industry, we’ve a long way to go before people are saving anywhere near enough for retirement. But we’re off and running. Join us!

Wednesday, 16 August 2017

Deferreds - The Poor Relations

I’m of that age. Time to start looking at what pensions I’ve got and to consider when to take them. It’s a bit of a shock to have reached such an age, I have to say! I’ve spent most of my career planning other people’s retirement and never really thought about planning my own. But there you go – time waits for no man and all that.

My first foray into my very own pension-land wasn’t such a success though. I approached a life and investment company that had taken over the liabilities of a plan I had been part of a long time back. And was rather surprised to be told I had no pension with them! I was able to produce a deferred pension statement, and all was sorted. But it does beg the question as to what would happen if I were less prepared. How many others fail to sort out deferred pensions due to poor record keeping? Or, more likely, having gone away and failed to notify the provider of the new address.

The usual tracing processes mean that eventually, the deferred member will (hopefully) be found and the benefits sorted out. But there’s no doubt that deferreds – especially in closed DB schemes – are the poor relations in terms of communication.

I hope that the new plans for a pensions dashboard will help rectify this. And there’s legislation on the way requiring an annual statement for deferreds as well. The more frequent use of emails in record keeping is helpful too, as many people may move house but not change their email address.

Nevertheless, as I found out personally, deferreds need a bit more attention.

As to the amount I’ll be getting, well let's say I won’t be fully retiring just yet!


Friday, 29 April 2016

The Reason for Wrong Decisions

Well done to Darren Philp of People's Pension for the excellent presentation at this week's Pension Age Conference. He spoke on reasons people make the wrong decisions. So with some commentary of my own,  here's hoping I was listening properly:

1. Present Bias
This is simply the feeling that I can have the money now, take it out, use it, not save it.

2. Ostrich Effect
Head in the sand and the pension decisions may go away.

3. Optimism Bias
I really won't need to save that much as what I have will bring in loads of interest. Alternatively... I really won't need much in retirement...

4. Complexity Aversion Bias
Too much choice! What to do? Nothing.

5. Bandwagon Effect
What's everyone else doing? That must be right....

6. Confirmation Effect
Can someone please confirm what's best for me? Just tell me what to do!

The solution to these issues lies in clear communication at a simple level, good 'defaults' and a good deal of persistence from the employer/provider!

Wednesday, 25 February 2015

Common Sense and Efficiency

The latest research from Alliance Bernstein carries no surprises. It says that the consumer expects a common sense approaches to investment- a feeling of control but without certainty of outcome. A combination of good governance and a sensible default fund is expected. But consumer common sense also says it’s okay to expect a spread of outcomes at retirement.

What is also expected though is flexibility and freedom at retirement. That’s fine and good if we know what we’re doing. The NAPF tell us in Pensions Expert that we don’t know what we’re doing because the Government has failed to give us the detail. With 30 working days to go before the pension freedoms, what the consumer doesn’t want is someone telling them that ‘yes, the freedoms exist’, but ‘no, you can’t benefit from them because we don’t know what to do.’

Will we get the detail in time? Or has election fever already affected output?

Common sense and efficiency from the Government would be welcome right now.

Wednesday, 26 November 2014

Pragmatic Steps Into The Unknown

I welcome the common sense approach adopted by the Treasury in not, after all, trying to fine individuals who take a pension pot and fail to advise earlier pension providers they also have benefits with.

The revised guidance extends the deadline from 31 days to 91 days and that states that only active providers need be contacted. This gets around the problem that individuals may well have pensions with providers that they have simply forgotten about. I know that shouldn’t happen, but not everyone loves pensions as much as me – and you, presumably, as you are reading this.

Common sense has prevailed.

The major problem remains however.  I’m not sure anyone, including the government who introduced the changes, knows exactly what is going to happen when the full freedoms on pensions come into force. Will there be reckless decisions to cash in pensions? Will advice be adequate? How will the government react to those who take, spend and then come back, begging cap in hand?

One thing is for sure. To change the analogy, the genie is out of the bottle and no future government will be able to put him back.

A pragmatic step by the government with regard to individual fines. But nevertheless, it’s pragmatic steps into the unknown.

Tuesday, 16 September 2014

Instant Society

Yesterday was Pension Awareness Day. The BBC ran a pensions programme called Inside Out, looking at the pension cheats and the need to save. It even had a cameo performance from Steve Webb, chatting to pensioners on a bus.

Joan is 93. In the programme she comments on the cultural shift towards spending now.

'Nowadays, young people don't know how to save - because they've never had to save. It's a throwaway society. They've never had to make do and mend like we had to.'

There's something in that. In our instant, 40,000 googles-a-second society, everything is instant. Saving isn't.

Monday, 8 September 2014

Laughing All The Way FROM The Bank?

A survey from Fidelity, recorded in the Sunday Times, interviewing 500 people due to retire or planning to retire next year makes interesting reading. It suggests most are going to turn their backs on annuities and take all the cash they can. But how wise is this? Cash now, but poverty later?

Unless they are cautious with their new found wealth, they may well find it runs out a long time before they run out. Then what? In Australia, it’s called ‘double dipping’ – ie taking your pension as cash now and then relying on the State when you run out of money.

Is this what we can expect in the UK? Has the government relaxed the laws around pensions too much?

Monday, 16 June 2014

House Moves and Pension Moves

Just recovering from moving house, so therefore catching up a bit with all that has been happening in the world of pensions.

(Incidentally, well done to all the various third parties, institutions and providers –and especially the Post Office- for responding so well to our house move. All except BT that is. Did you know you can’t order broadband if there is no recognised house phone? Actually there is a house phone- but it’s been offline with the house being empty. Anyway, BT rant over....)

The main pension move of course has bee CDC’s. Not new, but a new energy for the idea post Queen’s Speech. And Steve Webb linking it to his Defined Ambition project. Is it really DC+ (to use a Webb phrase)? Sort of.

Plus in terms of increased certainty by way of volume. Plus in terms of lower costs, again due to volume. But not plus in terms of additional guarantees. The pot can still go down as well as up. There’s no protection even on pensions in payment.

I remember managing a Dutch CDC for a large international company. The news was not good one year. There were going to have to be reductions in pensions in payment. It was a hard one for the local Dutch company to manage in terms of a news story that could get out to the press. No one wants their pensioners to suffer. The US parent company didn't like it one bit. How did we get to this, they were asking? It was a communications nightmare.

What looks good on paper and works logically for pension professionals is still hard to explain to a member. Especially a pensioner who’s just found out they are getting less in their bank account each week.

Nevertheless, I think it’s a good step forward so long as we can manage the message with the members.

Wednesday, 7 May 2014

A Long Road


It’s pleasing to see the views in the press that the new DC flexibility could increase member savings (Pensions Expert). I agree. There is room for optimism. Fewer restrictions on the pension should result in more willingness to save.
Another article, this time in Professional Pensions, records the latest LV survey. The income of the average retiree is almost 24% less than the minimum wage. There’s a lot of stats behind that statement of course, but one thing is clear, the new flexibility HAS to increase member savings. The savings gap is growing. We’re on the right track, it’s a good start, but (to retain the track analogy), it’s a long road.

Thursday, 20 March 2014

Pensions Poverty

I welcome the budget changes to pensions. I really do. But the truth is, it’s benefits for the privileged offered by the privileged (to misquote Ed Milliband). Here’s a Facebook message that was posted today by Monika, a lady in my church:

Dear George Osborne,

I'm glad that future pensioners will be able to draw down their annuities and that people with the money to spare can put more of it into ISA's and that, probably those same pensioners can save via a Pensioner's Bond.

But please explain where those pensioners with little, or no, spare cash will be better off.

Personally, when I was a single working mother, I saved what I could in an annuity, only to find out when I retired, that, as it did not amount to £23,000 I was not allowed to withdraw it and had to receive an annuity of, wait for it, £12 a year (!). Even if I live to 100+ I'll never be able to draw out what I put in and now, because I've already retired, it's still locked away.


It seems to me that many pensioners will still not be any better off, despite the media's proclamations, so don't be surprised if you don't get my vote in the next general Election.

Her comments are pretty typical of the real issues we face. Pensions poverty is real.

And what’s worse, according to the Institute of Economic Affairs, we can’t do much about it either. They advise that promises made by successive governments have not been honoured from the existing tax base. So we can’t afford to pay what we’ve promised to pay, and according to IEA’s Philip Booth, ‘it is quite possible that we will not find our way through without serious social breakdown’.

That’s the sobering message behind the mild euphoria in the pensions industry provoked by yesterday’s budget announcements.

Tuesday, 3 September 2013

The Corporate Version of Caring for Your Parents


As you get older and your parents get frail, there comes a point when you have to decide how to care for them. If it’s a decision to put them in a care home, the costs have to be found. Often that will be through selling their home. And remember, it’s often your childhood home too. Sad that their care requires the sale of something with such precious memories.

When Defined Benefit plans were ‘invented’, they were affordable. A combination of longevity, market changes and strict accounting practices means that this is no longer the case. So what to do? The promises have been made. You need to care for those where a pension has been promised. So sometimes, you have to sell what is precious to you.

That’s what has happened this week with the Royal Geographical Society. In order to fund the pension promises, they are selling some of their precious artwork. Paintings that have been in their collection for over a century.

Sad that promises made require the sale of something so precious and irreplaceable. Witness the corporate equivalent of selling the parental home. But the ongoing care of the elderly has to be more important than even the most beautiful of paintings. Or houses for that matter. Or businesses too?.....

Monday, 19 August 2013

Doing Things Differently

The headlines in today's Telegraph make sobering reading for those in the pension industry:

'I lost £150,000 due to Nineties pension sales frenzy.' 

This refers to the mis-selling scandal of course and tracks the story of one ex-soldier who was persuaded to transfer to a personal pension from the Armed Forces Plan. Disastrous results. And with many of those poor decisions reaping a poor pension, we will be seeing more of this in the press as people reach retirement.

'Pensions' doesn't have a great reputation anyway and these stories are not going to help. Warren Buffett said 'it takes 20 years to build a reputation and five minutes to ruin it. If you think about that, you'll do things differently.' And we are doing things differently. But history and reputation are against us.