Showing posts with label communications. Show all posts

Thursday, 2 November 2023

Moving on, part 2

  I'm so glad you came by. But I have moved to two new sites.

My main blog can now be found at ralphturnerwriter.com

And anything to do with the revival in Leicester can be found at revivalinleicester.com

I do hope you will join me on our continuing journey together.

Monday, 27 May 2019

YOU CAN STILL FIND ME.....

I've retired from the pensions industry now (though if you have the odd trustee position, do shout!) So that means this blog is closed.

There's lots here though, especially to do with pensions communications, so do take a look through. And we're still not communicating well to members!

And finally, if you want to say 'hi', you can reach me at ralphturnerwriter@gmail.com. And my general blog is still operating: Mountain Climbing for Beginners. I hope to see you there.

"Never measure the height of a mountain until you have reached the top. Then you will see how low it was."
Dag Hammarskjold 

Wednesday, 20 June 2018

Brexit Mania Hits Pensions


The future of the well supported Pensions Dashboard is in doubt. And Brexit is the reason. The Government seem unable to consider anything other than Europe and our relationship within (or without) it. It means good local policy is being side-lined.

There’s a consensus that legislation is needed to introduce a compulsory Dashboard- a go-to place for all our pensions, held in one place and with all providers required to work with it . Everything in one place and set out in a standard way: What’s not to like?

Limited availability in the parliamentary calendar means the compulsion may not happen- or not any time soon.

With the legislation beginning to slip into the long grass, the Department for Work and Pensions (DWP) feasibility report including the broad proposals, has also been delayed. Due in March, then ‘late spring’, it’s still not here. The DWP are now saying it will appear 'in due course.' Yea, right. And of course, the DWP have no real incentive without a Government willingness to push forward.

One of the best and most far reaching ideas in terms of clear pension’s communication is in danger of not happening, only partially happening, or completely happening but at a date so far in the future we may as well go argue about Brexit.

Thursday, 26 October 2017

It’s Not Just About Costs

The announcement today from the Government with regard to cost transparency is welcome. It should not be hard for members to understand what they are paying – and what costs are being charged for both administration and investments.

There is one concern though- a rush to the lowest charges may not mean the best deal. There needs to be care involved in explaining costs. A higher administration charge in some cases may mean a local company DC plan can continue, rather than being swallowed up by one of the big providers, or by a master trust. And there’s a good reason for that additional cost if the result is a plan that is better suited to that company’s workforce, as well as it being better presented and explained.

As to investment costs being more transparent- about time too! But again, take care in explaining that lowest charges don’t always equate with best returns.

As employers and providers, we can’t just rely on costs being understood. Members need to understand the value of their pension plan, the fact that it’s tax efficient and that employer money is being paid in as well. These are basic things, but so often still misunderstood by a workforce that is apathetic to pensions. The employer and provider can’t afford the same apathy.

As always, pensions will remain complicated. And it's not just about costs. Good communication is key. Enthusiasm from the provider and employer sponsor is key too.

Monday, 11 September 2017

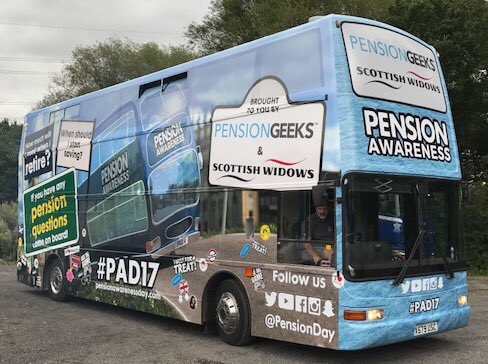
Pensions Awareness Day - On The Road


It’s year four. And it’s been quite a journey. From originally registering Pensions Awareness Day, to seeking support from the pensions industry (thank you!) to painting up a bus and taking it around the country…. It’s got bigger and better each year.

This year starts in Edinburgh, and the bus then moves on to Leeds, Birmingham, Cardiff and London. Over the week, we are expecting hundreds of people to come onto the bus, asking their questions about pensions. We will be giving away plenty of ‘freebies’ and with help from Pensions Wise, handing out loads of advice.

If you’re in the area, why not come over? This is the website with dates and times in each city:

PENSIONS AWARENESS DAY

As an industry, we’ve a long way to go before people are saving anywhere near enough for retirement. But we’re off and running. Join us!

Wednesday, 16 August 2017

Deferreds - The Poor Relations

I’m of that age. Time to start looking at what pensions I’ve got and to consider when to take them. It’s a bit of a shock to have reached such an age, I have to say! I’ve spent most of my career planning other people’s retirement and never really thought about planning my own. But there you go – time waits for no man and all that.

My first foray into my very own pension-land wasn’t such a success though. I approached a life and investment company that had taken over the liabilities of a plan I had been part of a long time back. And was rather surprised to be told I had no pension with them! I was able to produce a deferred pension statement, and all was sorted. But it does beg the question as to what would happen if I were less prepared. How many others fail to sort out deferred pensions due to poor record keeping? Or, more likely, having gone away and failed to notify the provider of the new address.

The usual tracing processes mean that eventually, the deferred member will (hopefully) be found and the benefits sorted out. But there’s no doubt that deferreds – especially in closed DB schemes – are the poor relations in terms of communication.

I hope that the new plans for a pensions dashboard will help rectify this. And there’s legislation on the way requiring an annual statement for deferreds as well. The more frequent use of emails in record keeping is helpful too, as many people may move house but not change their email address.

Nevertheless, as I found out personally, deferreds need a bit more attention.

As to the amount I’ll be getting, well let's say I won’t be fully retiring just yet!


Wednesday, 17 May 2017

Dear Next Government.....

I’m not sure that pensions will be one of the major battle grounds in this election, and if it is, it may tend to be around the ‘triple lock’ headlines.

That would be missing the point. We need clarity form the next government in terms of the communication of pension plans. I appreciate the initiatives towards one design for future benefit statements, but the sooner the better.

Clarity on the future management and promotion of auto-enrolment is key. As is confirmation of state pension benefits and ages.

All this should lead to a harmonised approach to communicating pension benefits. Too many benefit statements have reams of small print. Most of it is legislative. Some of it is pension lawyers having too strong a say in the look and feel of communications.

It doesn’t help that we have the dreaded statutory money purchase illustrations. Loads of caveats. Tons of small print. So unhelpful.

Dear next government…. Please simplify communications. Cut the small print. Clarify the main figures. Help people understand.

Thursday, 9 February 2017

The Daily Mail Fabricates News - Not so new news

The news out today that the Daily Mail fabricates news is not such new news. Working in the pensions industry, their regular pension headlines have been the bane of many a pensions manager.

The Mail had the ability to pick up on a half-truth and fabricate a complete story out of it. The results were usually concerned members of pension schemes panicking that they have the right plans in place.

The negative Mail headlines for pensions caused unnecessary grief and may well have stopped employees from joining a pension plan they should have been part of.

The poor journalism on display at the Mail has found them out.

Tuesday, 3 January 2017

New Year Wishes

There will be a lot in the pensions press over the next few weeks relating to the New Year. A New Year goes along with New Year resolutions and wishes.

In pension terms, wishes are likely to revolve around simplified administration, easier investment access to difficult products and a plea to the politicians to be left alone. Some wishes may get granted- the current initiatives relating to data management are both welcome and likely to succeed. Investment products will simplify. And possibly – possibly – the Chancellor has enough on his plate not to interfere further in pensions.

The missing wish, though, is always there. Every year. Better communications. Too many people don’t know enough about their pension. Too many people without a pension are not concerned enough to do something about it.  

About now, with New Year resolutions in mind, the pension manager is returning to work and budgeting to communicate more efficiently. Maybe some focus groups. Maybe a survey. Maybe different methods of communicating including print and electronic.

Somewhere around mid-February, reality and the new budget process sets in and the dreams are forgotten. Another year of ‘doing what we’ve always done’ at as low a cost as possible.

So here’s a New Year wish. Please keep communications in your new year budget. Budget to use some pension communication experts. And change next years’ wishes.

Tuesday, 1 November 2016

The Barrier of Words

As passionate pensions people we want to communicate well. We want people to understand their pension and appreciate its value. But we are often stopped from communicating well by our own blind spots. In fact our words can be a barrier to getting the message across.

The Technical Barrier

Too often we assume we are being clear with our pension communications when it is nothing but gobbledygook to the recipient. We are so wrapped up in the industry we work in, we are not aware of the pension jargon we are using. Glossaries help, but better to write plainly and assume the reader knows nothing about the subject. If you talk about ‘hedging’ your investments, people are likely to be thinking of a green bush in the garden. If you speak of commutation, people will think you are talking about travelling to work…. You get the picture!

The Cultural Barrier

This is a more subtle communication issue. Not all companies are the same. Many may be UK companies and have a certain style of communicating. Others may be US companies- generally the business language is sharper and more to the point.

I work part time for a community based charity. Here the language is very different to anything I have experienced in the commercial world. You can’t just dive in to the issue you want to email on, for example. There has to be a bit of a ‘how are you’ and a conversation would typically end with ‘blessings’ rather than ‘cheers’ or ‘yours sincerely.’

So when you’re speaking about pensions – typically a ‘foreign language’ to any organisation, it’s important to first asses the culture of the company you are working with.

The Functional Barrier

As an occasional consultant for Pension Geeks, it’s interesting pitching business. No matter what the potential client may say, you are being assessed against the incumbent communications company. And, sometimes without the client being aware of it, they are expecting you to be the same, and possibly to charge the same. (As we’re smaller with fewer overheads, the fees are usually a good conversation to have).

That same functional barrier can work in presenting pensions to a non-specialist audience. They have an expectation that they won’t understand it, sadly based on earlier pension events or (often inaccurate) articles they have read in the press.

Words can be a barrier. And there’s the challenge!

Thursday, 8 September 2016

Majoring on the Minors

My good friend Henry Tapper makes an interesting point in one of his recent blogs (where does he get the energy to write so much?!) He points out that we keep going on about investment freedom of choice when most people just need a good default choice.

That’s backed up by what we find on the Pensions Awareness Day bus. So many people come on board with pension questions. And so many more with a simple statement: ‘Tell me what to do.’

We are catering too often for the financial expert, and not enough for the man or woman on the street. It may feel uncomfortable to ‘tell’ people what to do but that’s what they want.

If we could just put as much energy into developing effective default options as we do into developing the next big investment idea that is only of interest to the minority, we really would be getting somewhere.

Thursday, 2 June 2016

Benefits that Drive Value

I met a Finance Director of a medium sized business recently. In our brief conversation, he made it clear he did not value the benefits his company provided to staff and saw them simply as an additional overhead.

If I’d had longer to talk, I’d have said more than I did. This is my follow up letter. (Not actually sent as I didn’t get his details!)


Dear Finance Director

It was good to meet you the other day.

I appreciate our conversation was a brief one, but if I’d had longer to chat, this is what I would have said….

I understand business is tough and from your point of view, additional benefits on top of salary are just overheads to be dealt with. But have you considered what you could do with those benefits at little extra cost to you?

Most employees don’t value their benefits either- mostly because employers don’t communicate them too well. I’m guessing that would include you- why communicate what you don’t value as a business manager? But the benefits all have value. The pension has matching employer contributions. That’s like free pay to your staff. Even the flexible holidays have a value, and the discounted affinity benefits have little cost to you but significant value to those who use them.

I guess I’m asking you to have another look at what you offer.  With the right communication, you can turn benefits from perceived business costs to providing a competitive edge for your company. Good benefits properly explained promote your business above and beyond your competitor who does not have those benefits- or does not bother communicating them. Small communication costs can provide a significant competitive edge, driven from staff wellbeing and a value well beyond the benefits themselves.

Benefits don’t have to be overheads. They can be your business case for future profitability.

Yours sincerely

Friday, 29 April 2016

The Reason for Wrong Decisions

Well done to Darren Philp of People's Pension for the excellent presentation at this week's Pension Age Conference. He spoke on reasons people make the wrong decisions. So with some commentary of my own,  here's hoping I was listening properly:

1. Present Bias
This is simply the feeling that I can have the money now, take it out, use it, not save it.

2. Ostrich Effect
Head in the sand and the pension decisions may go away.

3. Optimism Bias
I really won't need to save that much as what I have will bring in loads of interest. Alternatively... I really won't need much in retirement...

4. Complexity Aversion Bias
Too much choice! What to do? Nothing.

5. Bandwagon Effect
What's everyone else doing? That must be right....

6. Confirmation Effect
Can someone please confirm what's best for me? Just tell me what to do!

The solution to these issues lies in clear communication at a simple level, good 'defaults' and a good deal of persistence from the employer/provider!

Tuesday, 5 April 2016

Being Bold on the Benefits of Pensions

Helen Morrisey’s clarion call in Professional Pensions to be ‘bold on the benefits of pensions’ is welcome.

So often, as pension professionals, we get caught up in the minutiae of the pension issues and forget the big message. But the big message is a simple one and needs saying as frequently as possible. And as simply as possible.

On the bus tour linked to Pensions Awareness Day, nearly 600 people came onto the bus during the week. And what did they ask? Details as to how S2P is changing? No. How to maximise their AVCs? No. What investments will give the best return? No.

Their questions were simple (see previous blog):

–      ‘What’s a state pension?’

–      ‘Do I get any pension from the Government?’

–      ‘Does my employer offer a pension?’

–      ‘Do I have to offer a pension?’ (from an employer)

–      ‘It’s all too complicated’

–      ‘There’s too much choice’

–      ‘Tell me what to do’

To quote Helen, ‘we need something simpler, cleverer and bolder’. Come on pensions communications companies- let’s be hearing from you!

Friday, 18 December 2015

Pension Awareness Day - Keeping it Simple

In September, the Pension Awareness Day bus travelled from Edinburgh to Manchester, to Leeds, to Birmingham, to London.
 

Over 600 people came on board during the week. Pension Wise were there, with different teams at each location. And the good people of Scottish Widows and People's Pension were on hand to help. Local radio broadcast us. Local newspapers interviewed us. An the pensions press supported us. (Thank you Pensions Insight and Professional Pensions for your encouragement.)

And what did those 600 people ask or say? Here's a sample:
–‘What’s a state pension?’
–‘Do I get any pension from the Government?’
–‘Does my employer offer a pension?’
–‘Do I have to offer a pension?’ (from an employer)
–‘It’s all too complicated’
–‘There’s too much choice’
–‘Tell me what to do’
 
You don't get much more basic than that. For all our pensions knowledge, sophisticated communications and strange looking monsters courtesy of the Government, we still need to keep to the simple messages.

Thursday, 20 August 2015

Mirror.... Signal.... Manoeuvre...

Mirror... Signal.... Manoeuvre....  And off we go.

This years' Pension Awareness Day is gathering pace. And it's making even more of an impact as a bus is driven from Edinburgh to London via Leeds, Manchester and Birmingham.

The message is simple:  to promote the importance of saving for the future and to alert the nation that it is not saving enough for retirement.

If you're a pensions professional, a pensions company, or just plain interested in pensions, why not join us? It's not too late to sponsor the campaign. You get a lot of publicity - and more to the point, it's a strong altruistic statement that you care that the next generation has a pension!

Get on board! Here's the link: Pension Awareness Day.


Tuesday, 21 April 2015

Translating Pensions

Well done to Louise Farrand of Pensions Insight for her blog on pension phrases she would ban. I agree ‘On-Boarding’ is not a verb and never should be!

It got me thinking…..

How do non-pension people understand the jargon we throw at them? Maybe they don’t.

Here’s my own selection of pension phrases that may have very different meanings for the population at large. There’s a few you may have to think about first. Any more suggestions?


Abatement – A posh flat

Accrual – The opposite of kind

Actuaries - Flying performers

Amortisation – French for love on a train

Blended – A milk shake

Commutation – Travelling to work

Concurrency – A payment method using large shells

Discontinuance Basis – How shops sell end of line products

Fiduciary – Fido’s friend sees Harry (think about it….)

Glide path – Slipping over on a night out with the lads

Longevity Swap – Exchanging time share apartments

Middleware – Clothes worn in Lord of the Rings

Mortality Drag – Dangerous car racing

Offsetting – Losing at tennis

Pre-Crystallisation – Going into a jewellers shop

QROPS – Wheat

Tactical Asset Allocation – Winning on a games show

Targeted Return – Winning on a games show

Time Weighted Return – Getting fat

Wrap – From Pret

Yield – Wrestling manoeuvre

Zombie Fund – Clothes purchased for Emo wardrobe

Tuesday, 14 October 2014

Ninth But Slipping

We’re ninth again. The same as last year. But for how long?

Mercer’s Worldwide Global Pension Index puts the UK behind Denmark, the Netherlands, Australia and Chile among others, but well ahead of France, Italy, China and India.

The warning is though that with the new reforms (the Taxation of Pensions Bill was published today), we will slip down the rankings. More freedom to take a pension in various forms comes with a health warning. If savers can’t manage those savings well and spend their pension pot before they die, then they fall back on the State. It’s happened in Australia (called ‘double dipping') and could happen here.

In the name of freedom, our rankings may fall.

So much depends on good communication and advice. Osborne is enjoying positive pension headlines today with the publishing of the Pensions Bill, but if the government don’t back it up with adequate education and advice, we’ll be slipping down that table.


Saturday, 11 October 2014

Why We Provide A Pension

Here's a good reason why we work so hard to ensure there are pensions for people.


Thursday, 2 October 2014

The Left Hand Doesn’t Know What the Right Hand is Doing

This is an oft-used idiom with a Biblical foundation (‘But when you give to the needy, do not let your left hand know what your right hand is doing’: Matthew 6:3). In its original context, it’s used positively. But we’re talking  pensions here and I want to use it negatively!

Professional Pensions writes about the decision to have a number of different organisations dealing with pensions guidance. There’s TPAS, the Money Advice Service, a new offshoot of TPAS and a new directly controlled Treasury operation.

Three organisations and four delivery mechanisms.

Back to the quote. On the basis that there will not be enough resource put in place, how long before chaos ensues?!